FleetPartners Group Limited is a leading provider of vehicle leasing, fleet management, and salary packaging solutions across Australia and New Zealand. The company serves businesses of all sizes, government clients, and consumers through a mix of novated leases, operating leases, and commercial vehicle management.
Why did we invest?
FPR generates a large proportion of its earnings from recurring lease and fleet management fees, providing visibility and predictability to its cash flows. Its long-term lease contracts create resilience across economic cycles.
Following the completion of the divestment of non-core operations and a rebrand from Eclipx Group to FleetPartners, the company emerged leaner and more focused. The balance sheet was strengthened, unlocking significant shareholder value.
The increasing shift to outsourcing fleet operations, combined with the growing popularity of novated leasing due to rising car ownership costs and favorable taxation, supported a growing addressable market.
During COVID, vehicle supply shortages drove elevated prices for used cars. As leases matured, FleetPartners benefited from unusually high end-of-lease sale profits, boosting margins and earnings between FY21 and FY23. This provided a cyclical earnings uplift above underlying lease income.
FleetPartners began to actively position itself for the electrification of vehicle fleets, partnering with OEMs to offer EV leasing options and establishing EV-compatible infrastructure for clients. Government incentives and growing corporate ESG mandates supported this initiative.
Management executed a disciplined cost-reduction strategy while also initiating capital returns to shareholders through share buybacks highlighting balance sheet strength and commitment to shareholder returns.
Entry price
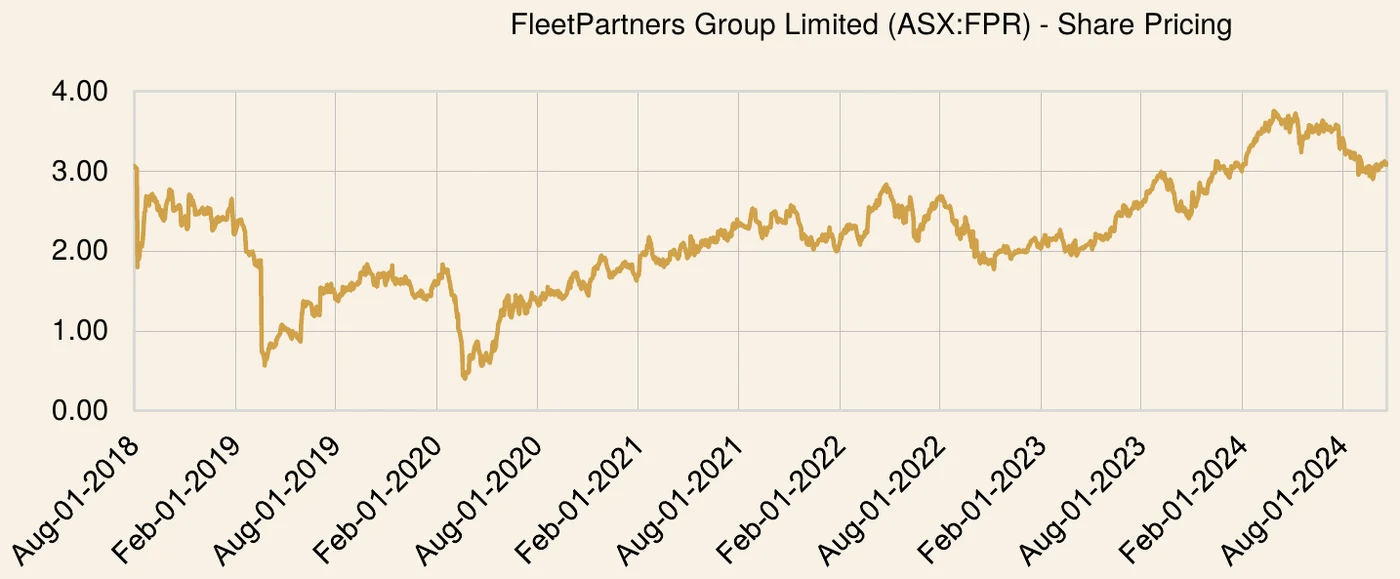
Began initially purchasing shares in August 2018 at $1.97 and continued to purchase over time with an average purchase price of $1.84.
Share price over the investment period. Source: S&P Capital IQ.
Why did we sell?
Full valuation realised
By 2024, FleetPartners had largely realised its earnings upside from elevated end-of-lease gains as vehicle supply improved and used car prices softened.
NPAT was expected to revert to a more normalized range of $70–75m, from ~$96m FY23 peak implying limited further earnings growth in the absence of significant lease book expansion.
We also identified emerging competitive pressures in novated leasing from fintech entrants and regulatory scrutiny around fringe benefit exemptions for EVs.
The stock had re-rated to reflect full value, and incremental returns were less compelling relative to other opportunities.
Investment outcome
Began initially purchasing shares in August 2018 at $1.97 and continued to purchase over time with an average purchase price of $1.84.
Sold at an average sale price of $3.20 with the last sale in October 2024.
Gain of 73.4% on our investment over the period, equating to a money weighted IRR of approximately 24.2%.
*Past performance is not indicative of future performance. This is general information only and should not be construed or relied upon as legal, financial or professional advice. Accordingly, the recipient should seek independent professional advice as to the risk, financial, taxation and other implications of investing. Microequities Asset Management Pty Ltd is a Corporate Authorised Representative (CAR 462438) of AFSL 287526.