Healthia is a diversified allied healthcare provider operating a national network of clinics across podiatry, physiotherapy, optometry, and other specialties. With over 300 clinics, it focuses on community-based care supported by an integrated back-office platform.
Why did we invest?
Recurring Revenues & Network Effect: Healthia generated a large proportion of revenue from recurring patient services across its growing clinic network. Its disciplined acquisition strategy and regional dominance supported economies of scale and high patient retention.
Favourable Industry Tailwinds: Rising demand for allied health services driven by Australia’s ageing population, increased chronic disease prevalence, and government healthcare support policies underpinned long-term structural growth.
Proven Roll-up Strategy & Operational Synergies: Healthia consistently executed a value-accretive roll-up model, acquiring and integrating clinics with disciplined financial criteria. Centralised systems and back-office functions unlocked operational efficiencies and margin expansion.
Entry price
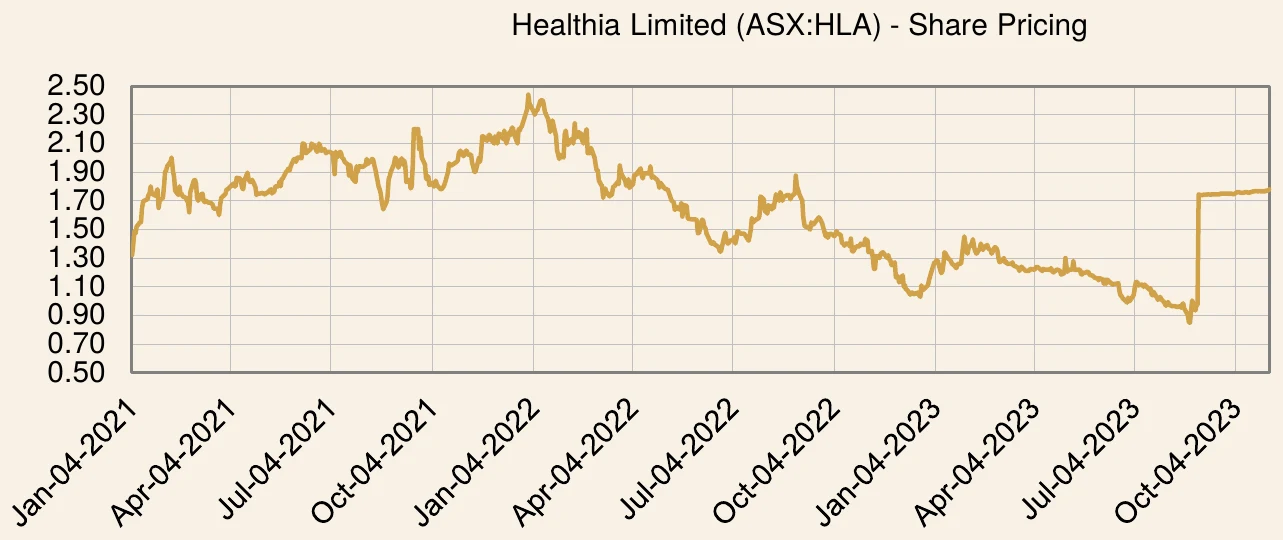
Began initially purchasing shares in early January 2021 at $1.29 and continued to purchase over time with an average purchase price of $1.43.
Share price over the investment period. Source: S&P Capital IQ.
Why did we sell?
Acquisition by Pacific Equity Partners (PEP)
In October 2023, Healthia entered a Scheme of Arrangement to be acquired by PEP at $1.80 per share, a 39.6% premium to the 1-month VWAP.
The transaction offered a compelling valuation relative to industry peers and our internal analysis.
With a full valuation achieved and limited remaining upside, we exited and redeployed capital to higher conviction opportunities.
Investment outcome
Began initially purchasing shares in early January 2021 at $1.29 and continued to purchase over time with an average purchase price of $1.43.
Sold at an average sale price of $1.75 with the last sale in November 2023 at $1.78 prior to the Scheme completing.
Gain (including dividends received) of 23.7% on our investment over the period, equating to a money weighted IRR of approximately 19.7%.
*Past performance is not indicative of future performance. This is general information only and should not be construed or relied upon as legal, financial or professional advice. Accordingly, the recipient should seek independent professional advice as to the risk, financial, taxation and other implications of investing. Microequities Asset Management Pty Ltd is a Corporate Authorised Representative (CAR 462438) of AFSL 287526.