Text S.A. (previously known as LiveChat Software) is a Polish software company specialising in customer service and artificial intelligence solutions. It offers a suite of tools for B2B and B2C communication, including popular platforms like LiveChat, ChatBot, and HelpDesk.
Why did we invest?
Attractive valuation with structural growth exposure: At the time of our initial purchase, TEXT traded at conservative valuation multiples, despite operating in a secularly growing industry driven by digital transformation, compliance, and data security mandates.
High recurring revenue and client stickiness: The company had over 70% recurring revenue via license renewals, maintenance, and long-term contracts, with customer relationships spanning decades in some cases.
Consistent profitability and cash generation: TEXT maintained NPAT margins in the mid-to-high 40s, underpinned by a lean cost structure and low capital intensity, resulting in strong free cash flow conversion.
Undervalued microcap with limited coverage: As a microcap listed on the Warsaw Stock Exchange, TEXT was largely overlooked by institutional investors, creating an opportunity to acquire a quality asset at a discount to intrinsic value.
Internal innovation-led growth: Unlike many competitors that grew through acquisition, TEXT focused on internally developed software, providing higher ROI, better integration, and control over the product roadmap.
Tailwinds from digitalization in the public sector: EU-backed digitization initiatives across Poland and Eastern Europe further supported demand for TEXT’s workflow automation solutions, especially in government and regulated sectors.
Entry price
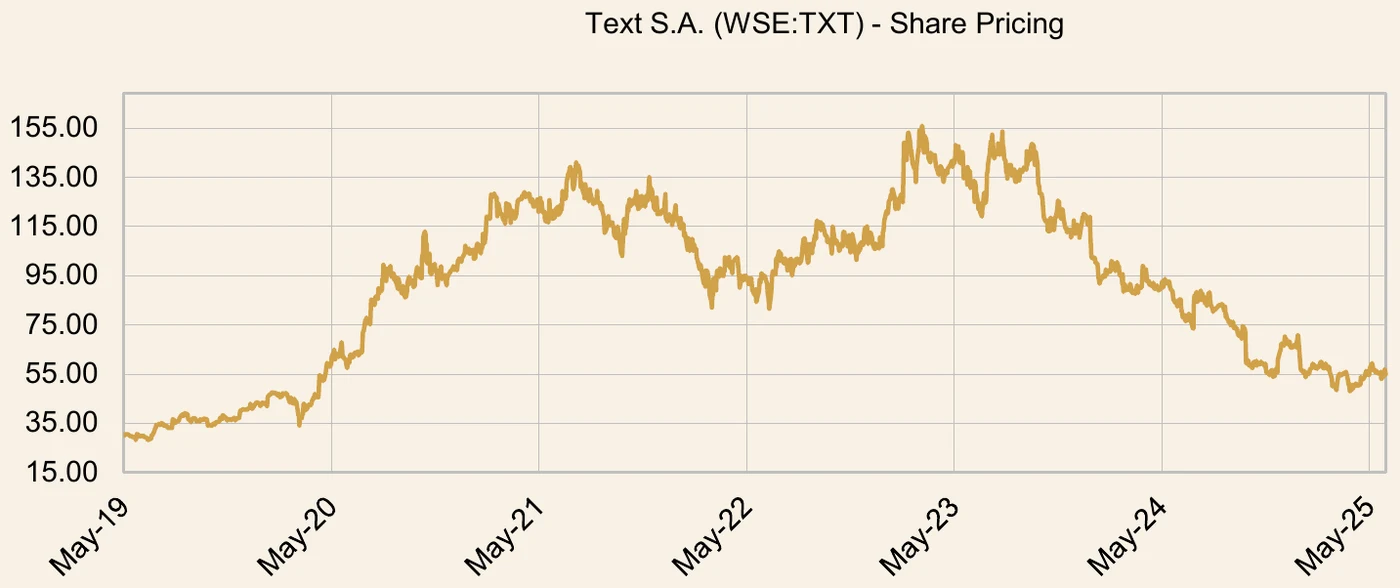
Began initially purchasing shares in May 2019 at 30.16 PLN and continued to purchase over time with an average purchase price of 32.82 PLN.
Share price over the investment period. Source: S&P Capital IQ.
Why did we sell?
Diminishing Margin of Safety
Valuation catch-up: In the period 2023-25, TEXT’s share price had more than doubled, with its EV/EBITDA multiple expanding as investors re-rated its recurring revenue and growth outlook.
Slowing top-line growth: While recurring revenues remained stable, new client acquisition and upselling began to decelerate, possibly due to saturation in core markets.
Competitive intensity rising: Large software vendors and cloud-native entrants started to gain traction in TEXT’s core verticals, raising concerns about long-term pricing power.
Capital recycling: With our investment thesis largely playing out and future upside more modest, we opted to redeploy capital to higher-growth microcap opportunities.
Investment outcome
Began initially purchasing shares in May 2019 at 30.16 PLN and continued to purchase over time with an average purchase price of 32.82 PLN.
Received circa 17.19 PLN in dividends per share over the investment period.
Sold at an average sale price of 90.85 PLN with the last sale in June 2025.
Gain of 309.8% on our investment over the period, equating to a money weighted IRR of approximately 56.4%.
*Past performance is not indicative of future performance. This is general information only and should not be construed or relied upon as legal, financial or professional advice. Accordingly, the recipient should seek independent professional advice as to the risk, financial, taxation and other implications of investing. Microequities Asset Management Pty Ltd is a Corporate Authorised Representative (CAR 462438) of AFSL 287526.