Vocus is a specialist fibre and network solutions provider, operating critical telecommunications infrastructure across Australia and New Zealand. It owns and manages more than 30,000 km of fibre and offers data, internet, voice, and network services to enterprise, government, wholesale, and residential customers. Vocus operates under three main business divisions: Vocus Network Services, Vocus New Zealand, and Retail & Consumer.
Why did we invest?
Strategic Infrastructure Ownership & National Scale: Vocus owns and operates one of Australia’s largest fibre networks, providing a substantial moat and pricing power in the enterprise and government segments.
Defensive Revenue & Diversified Exposure: The company generates a significant portion of revenue from long-term contracts with government and large corporates, ensuring revenue visibility and resilience to economic cycles.
Turnaround & Operational Focus: Following a period of underperformance, new management initiated a turnaround plan centred on disciplined capital allocation, simplification of operations, and margin enhancement across core divisions.
Entry price
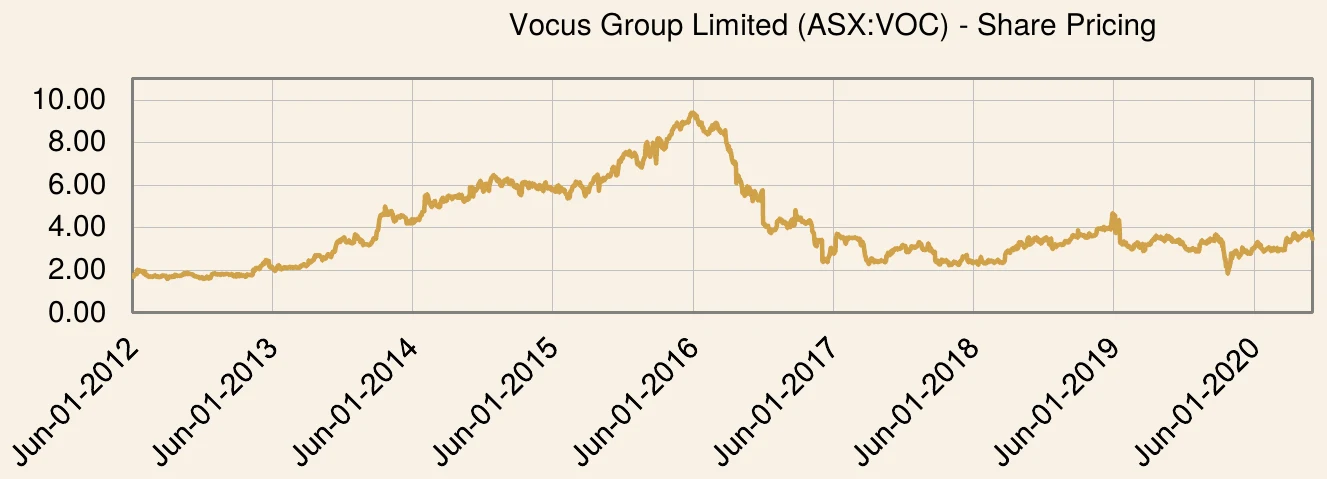
Began initially purchasing shares in July 2012 at $1.63 and continued to purchase over time with an average purchase price of $2.68.
Share price over the investment period. Source: S&P Capital IQ.
Why did we sell?
Operational and financial underperformance
Prolonged underperformance of the Retail Segment, despite strength in the enterprise and government divisions. Vocus’s retail broadband business continued to underperform, facing intense price competition from NBN providers and declining margins.
The turnaround strategy, announced by the new CEO in 2018, was still in early stages by 2020. Key structural and cultural reforms were underway, but the complexity and duration of implementation introduced elevated execution risk without immediate financial upside.
The company posted flat or modestly declining EBITDA margins in FY20 despite infrastructure ownership, signalling operational inefficiencies or underutilisation of assets. Additionally, revenue growth remained subdued across segments, weighing on investor confidence in near-term performance.
Vocus was undertaking substantial network investment especially in the Vocus Australia-Singapore Cable (ASC) and fibre backhaul, but the monetisation of these assets was slow and returns uncertain in the short term. This capital intensity diluted free cash flow and reduced the company's ability to reward shareholders.
Investment outcome
Began initially purchasing shares in July 2012 at $1.63 and continued to purchase over time with an average purchase price of $2.68.
Sold at an average sale price of $3.59 with the last sale in October 2020.
Gain of 34.1% on our investment over the period, equating to a money weighted IRR of approximately 35.3%.
*Past performance is not indicative of future performance. This is general information only and should not be construed or relied upon as legal, financial or professional advice. Accordingly, the recipient should seek independent professional advice as to the risk, financial, taxation and other implications of investing. Microequities Asset Management Pty Ltd is a Corporate Authorised Representative (CAR 462438) of AFSL 287526.