National Veterinary Care operated a network of veterinary clinics across Australia and New Zealand. The company provided veterinary services, as well as a range of complementary services such as training, procurement, and business support to independent clinics via its “Integrated Services” division. NVL pursued a growth strategy underpinned by acquisitions and organic clinic performance improvements.
Why did we invest?
Defensive Industry with Recurring Demand: Veterinary services are considered essential and typically resilient across economic cycles. Pet ownership trends supported steady and growing demand for veterinary care.
Attractive Clinic Acquisition Model: NVL employed a disciplined acquisition strategy of profitable, well-managed clinics. Acquired clinics were typically earnings accretive, and NVL demonstrated operational expertise in integrating and improving them.
Operating Leverage & Margin Expansion: The company benefitted from economies of scale, centralized procurement, and back-office functions, driving improved margins as the network grew.
Strong Management Execution: The leadership team had a demonstrated track record in executing the company’s “buy and build” strategy, with a disciplined approach to valuation and integration.
Entry price
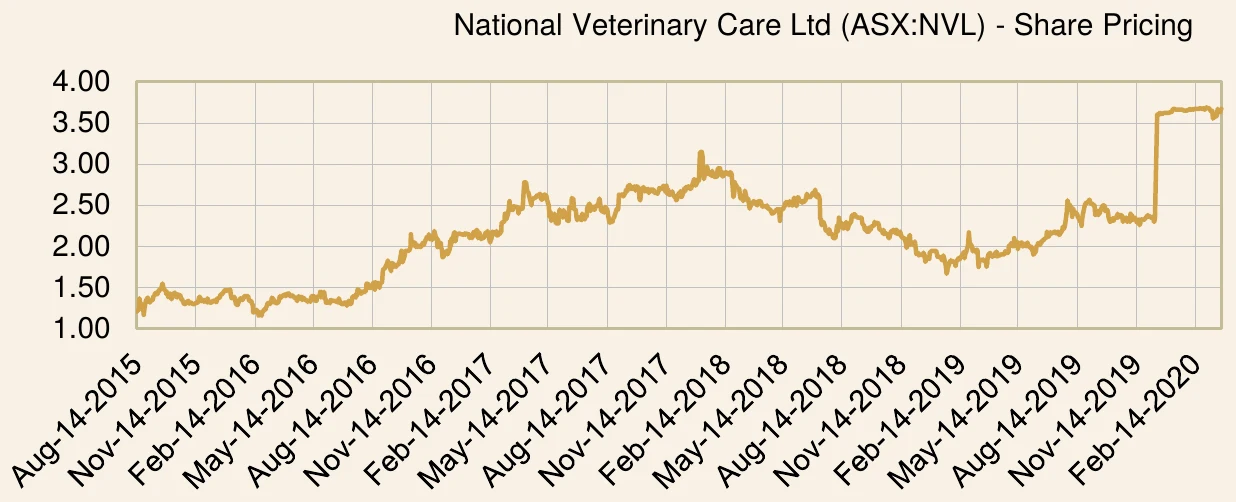
Participated in the IPO of July 2015 at $1.00 and continued to purchase shares over time with an average purchase price of $1.78.
Share price over the investment period. Source: S&P Capital IQ.
Why did we sell?
Acquisition by VetPartners
In January 2020, National Veterinary Care received an acquisition proposal from VetPartners, an Australasian veterinary consolidator backed by global private equity firm National Veterinary Associates (NVA).
Shareholders received $3.70 in cash per share, representing a 56% premium to the pre-announcement share price.
Given the full valuation realised and limited upside beyond the offer, we exited the position in line with our value realisation strategy.
Investment outcome
Participated in the IPO of July 2015 at $1.00 and continued to purchase shares over time with an average purchase price of $1.78.
Sold at an average sale price of $3.63 with the last sale in April 2020 tendering the last lot into the scheme at $3.70.
Gain of 108.3% on our investment (including dividends received) over the period, equating to a money weighted IRR of approximately 30.1%.
*Past performance is not indicative of future performance. This is general information only and should not be construed or relied upon as legal, financial or professional advice. Accordingly, the recipient should seek independent professional advice as to the risk, financial, taxation and other implications of investing. Microequities Asset Management Pty Ltd is a Corporate Authorised Representative (CAR 462438) of AFSL 287526.