PITECO is a leading Italian provider of corporate treasury and financial software solutions. Headquartered in Milan, the company offers mission-critical applications that help enterprises manage liquidity, payments, cash flow forecasting, and financial risk. With a growing presence in international markets and a robust recurring revenue base, PITECO is positioned as a digital enabler in the enterprise fintech space.
Why did we invest?
Undervalued niche software leader: PITECO operates in a highly specialized, sticky software segment with high switching costs. It traded at compelling valuation levels despite its strong margins and defensive recurring revenue base.
Strong financial profile: The company boasted EBITDA margins above 30% and healthy free cash flow conversion, supported by its SaaS and license maintenance revenue streams.
Resilient business model: Mission-critical treasury systems are deeply embedded within clients' operations, resulting in low churn and consistent growth, even during economic downturns.
Expansion through M&A: PITECO demonstrated a successful track record of bolt-on acquisitions, such as the U.S.-based Juniper Payments and RAD Informatica, enhancing its product suite and geographic diversification.
Tailwinds from digital transformation: Corporates are increasingly modernizing legacy treasury and risk systems. PITECO benefits from this secular shift, particularly in Europe and the Americas.
Scalable technology platform: As more clients onboard cloud-based modules, the business benefits from operating leverage and expanding recurring revenue.
Entry price
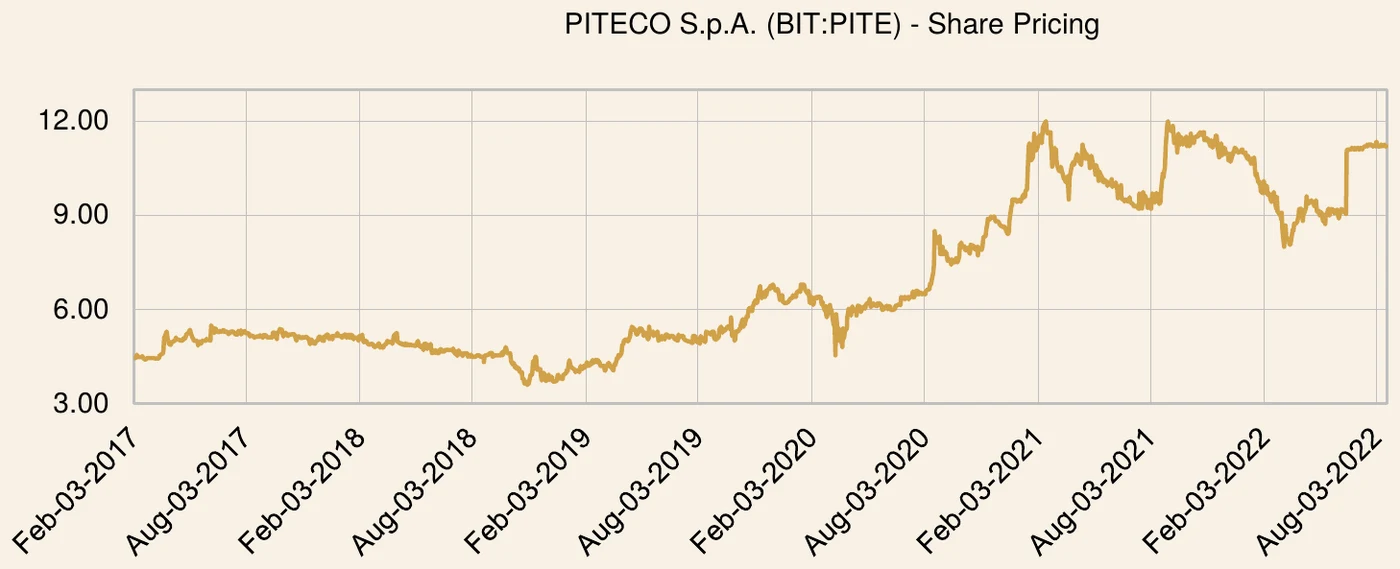
Began initially purchasing shares in February 2017 at €4.39 and continued to purchase over time with an average purchase price of €4.80.
Share price over the investment period. Source: S&P Capital IQ.
Why did we sell?
Tender Offer by Limbo Srl
In June 2022, Limbo Srl a company indirectly controlled by Lillo S.p.A., the principal shareholder of PITECO launched a voluntary public tender offer (OPA) to acquire the remaining 37.98% of PITECO shares it did not already own. The offer was priced at €11.25 per share, representing a premium of 23.2% to the 3 month VWAP.
Re-rating of valuation multiples: As PITECO’s growth outlook and quality became better appreciated, its EV/EBITDA multiple expanded, diminishing future upside.
Execution risks around international growth: While global expansion was promising, it introduced operational complexity, especially post-COVID.
Capital redeployment opportunity: As the market began to fully price in PITECO’s strengths, we reallocated capital toward opportunities with more compelling risk-reward profiles.
Investment outcome
Began initially purchasing shares in February 2017 at €4.39 and continued to purchase over time with an average purchase price of €4.80.
Received circa €0.444 in dividends per share over the investment period.
Sold at an average sale price of €10.69 with the last sale in August 2022 at €11.25 in the tender offer.
Gain of 130.5% on our investment over the period, equating to a money weighted IRR of approximately 25.3%.
*Past performance is not indicative of future performance. This is general information only and should not be construed or relied upon as legal, financial or professional advice. Accordingly, the recipient should seek independent professional advice as to the risk, financial, taxation and other implications of investing. Microequities Asset Management Pty Ltd is a Corporate Authorised Representative (CAR 462438) of AFSL 287526.