Shaver Shop is a specialty retailer focused on personal grooming and beauty products, including hair removal, hair styling, oral care, and massage devices. The business operates a multi-channel model with retail stores across Australia and New Zealand, alongside a growing e-commerce platform. The company has built a reputation for product knowledge, customer service, and exclusive distribution agreements with leading global brands.
Why did we invest?
Defensive Retail Niche with Loyal Customer Base: Shaver Shop operates in a resilient retail segment focused on essential grooming needs. Personal care spending tends to remain stable across economic cycles, supported by recurring customer demand and gifting occasions.
Leading Category Specialist with Exclusive Brands: SSG’s deep product range, knowledgeable staff, and exclusive distribution rights for several international brands (e.g., Philips, Braun, Wahl) provide a strong competitive advantage in a fragmented market.
Multi-Channel Sales Growth: The company executed well on its omni-channel strategy, with consistent growth in online sales enhancing margins and broadening reach. E-commerce represented a scalable growth driver post-COVID.
Operational Efficiency and Cash Flow: Strong cost control, disciplined inventory management, and robust free cash flow generation allowed for regular dividends and strategic reinvestment into digital and store optimisation. Store economics are strong with all stores profitable and high sales per square meter and low cost of doing business.
Capital Management and Shareholder Returns: Management demonstrated prudent capital allocation, returning value to shareholders via dividends and buybacks, while maintaining a conservative balance sheet.
Entry price
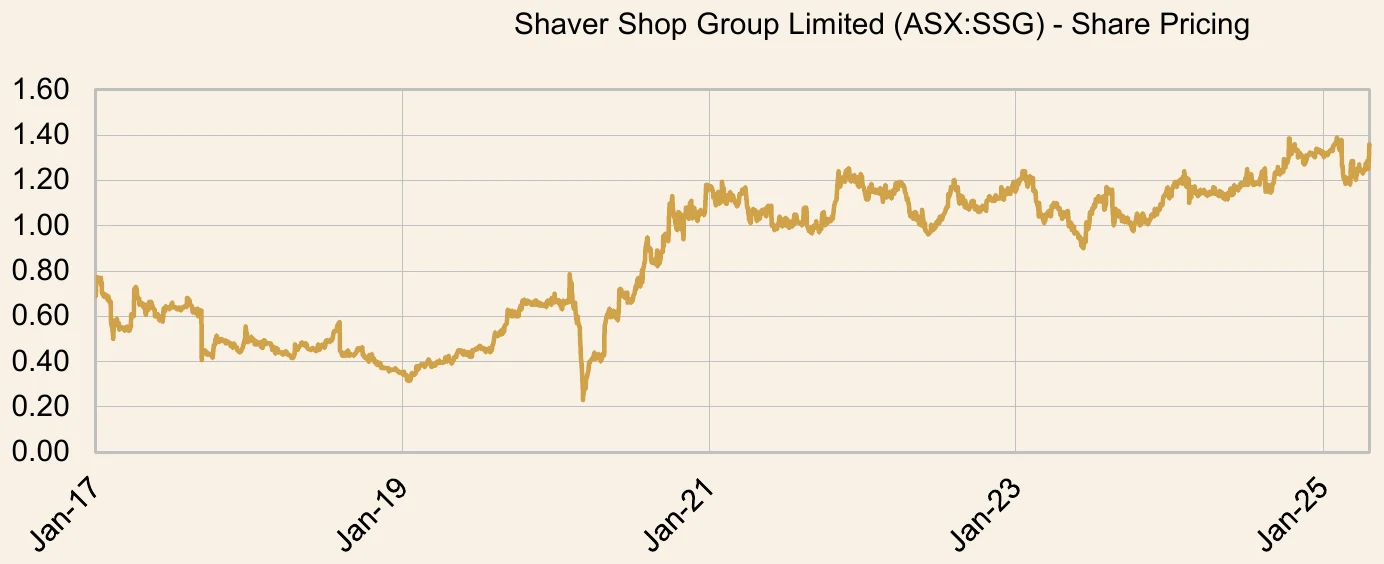
Began initially purchasing shares in January 2017 at $0.758 and continued to purchase over time with an average purchase price of $0.564.
Share price over the investment period. Source: S&P Capital IQ.
Why did we sell?
Valuation Realisation Amid Slowing Momentum
By 2024–2025, the investment thesis had largely played out. SSG had grown revenue, improved online channel penetration, and delivered consistent profitability.
The business was increasingly mature, and growth slowed post-COVID, particularly in categories that saw pull-forward demand.
Valuation became less compelling relative to slower growth prospects, with limited scope for multiple expansion.
Store network had reached maturity with management looking at other uses of capital such as acquisitions into adjacent retail categories, acquiring exclusivity distribution, white label products.
Investment outcome
Began initially purchasing shares in January 2017 at $0.758 and continued to purchase over time with an average purchase price of $0.564.
Received circa $0.609 in dividends per share over the investment period.
Sold at an average sale price of $0.974 with the last sale in May 2025.
Gain of 121.7% on our investment over the period, equating to a money weighted IRR of approximately 21.0%.
*Past performance is not indicative of future performance. This is general information only and should not be construed or relied upon as legal, financial or professional advice. Accordingly, the recipient should seek independent professional advice as to the risk, financial, taxation and other implications of investing. Microequities Asset Management Pty Ltd is a Corporate Authorised Representative (CAR 462438) of AFSL 287526.