Skullcandy designs and sells headphone and earphone products for the general audio and gaming markets. The company sells under three key brands, Skullcandy, Astro Gaming and 2XL.
Why did we invest?
Market leader in headphone and earphone by unit volume in its price category (sub $100)
Positive industry tailwinds including transition to higher value wireless headphones and earphones, growing gaming market, market share gains, growing international business and sales growing that had been masked by short term currency headwinds.
Strong balance sheet with approximately US$24m in net cash at 2015 year end (representing ~20% of the market capitalisation at time of purchase), which has grown to US$45m at the end of March 2016 (~33% of market capitalisation before the takeover bid).
2016 sales growth of mid to high single digits (i.e. 5%-8%) and EPS growth of mid-teens (i.e. ~15%).
Trading at circa 12x 2016 price-to-earnings multiple backing out its cash.
Entry price
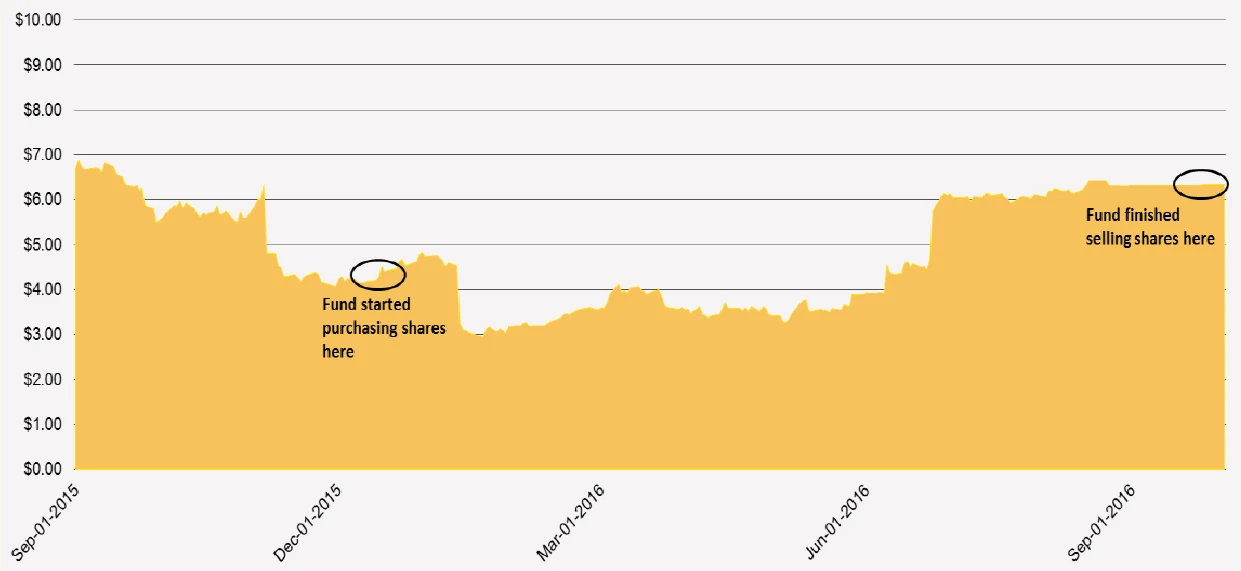
Began purchasing shares in December 2015 and continued until late January 2016. The average entry price was US$4.22.
Shares fell sharply in mid-January following a weak trading update for their Q4 2015 results. Reasons cited included strong USD being a headwind to gross margins, issues with one of its international distributors and weaker than expected market growth for the headphone market.
Share price over the investment period. Source: S&P Capital IQ.
Why did we sell?
Takeover offer
On Tuesday 7th July, Skullcandy founder Richard Alden (15.5% shareholder) revealed he and associated entities were pursuing a potential privatisation proposal of the company. As a result of the announcement, shares rose 16% to US$4.56.
On Friday 24th July, Skullcandy announced it had entered into a takeover agreement with Incipio, a maker of consumer and lifestyle products under the Braven, Tavik, ClamCase and Incase brands. The cash offer of US$5.75 per share was a 29% premium to Skullcandy’s closing price on 22nd July and 49% premium to the 90-day volume weighted average price. The agreement also gave Skullcandy 30 days to actively solicit a higher offer.
Shortly after market close on Friday 24th July, the company received a higher competing bid from existing shareholder Mill Road Capital to acquire the company for US$6.05 per share. Mill Road Capital already had a 9.8% shareholding.
After a number of counter offers, on Thursday August 18th, Skullcandy announced that they received a revised proposal from Mill Road to acquire Skullcandy for $6.35 per share, the Board determined that this was a superior proposal to Incipio’s offer, and recommended that shareholders accept the revised proposal.
Investment outcome
Invested, beginning in 2015, at an average purchase price of USD $4.22.
Sold at an average sale price of USD $6.35 in 2016.
Gain (excluding dividends received), of 50.5% on our investment over a 10-month period.
*Past performance is not indicative of future performance. This is general information only and should not be construed or relied upon as legal, financial or professional advice. Accordingly, the recipient should seek independent professional advice as to the risk, financial, taxation and other implications of investing. Microequities Asset Management Pty Ltd is a Corporate Authorised Representative (CAR 462438) of AFSL 287526.