Zix Corporation was a US-based provider of email security, threat protection, and data loss prevention solutions. Headquartered in Dallas, Texas, Zix served a wide range of small and medium-sized enterprises (SMEs), offering critical cybersecurity services such as secure email, encryption, archiving, and cloud-based threat protection. Its strong footprint in regulated industries such as healthcare, finance, and government underscored its position as a trusted cybersecurity vendor.
Why did we invest?
Mission-critical security platform: Zix offered indispensable email security and encryption services with high retention across SMEs operating in regulated environments. This mission-critical nature led to strong customer stickiness.
Recurring revenue with SaaS transition: The company’s increasing mix of SaaS-based revenue, over 80% at time of acquisition supported predictable cash flows and improved unit economics.
Undervalued strategic asset: Zix traded at modest valuation multiples relative to cybersecurity peers, despite a strong customer base and recurring revenue model.
Cross-sell synergy post-acquisition: The strategic acquisition of AppRiver in 2019 expanded Zix’s product suite, customer reach, and distribution via managed service providers (MSPs).
Cybersecurity tailwinds: As cyber threats have intensified, regulatory compliance requirements and increased IT spending created secular demand for Zix’s secure cloud offerings.
Attractive acquisition target: Consolidation in the cybersecurity sector made Zix a likely M&A candidate given its robust channel relationships and growing recurring base.
Entry price
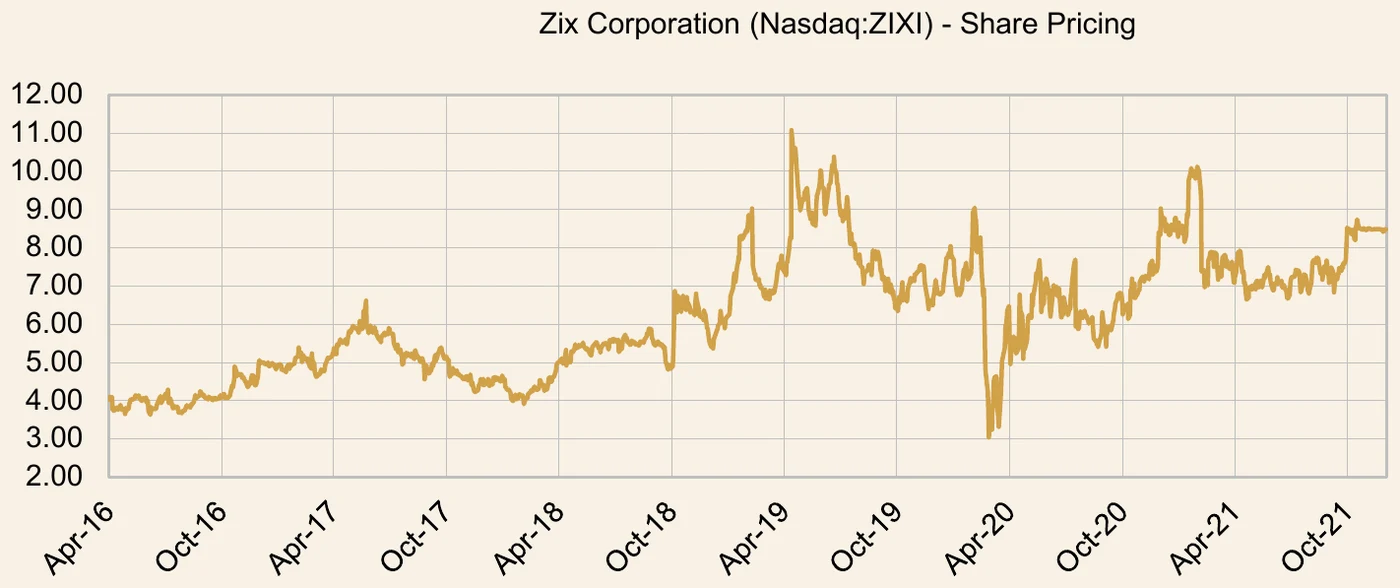
Began initially purchasing shares in April 2016 at USD $3.99 and continued to purchase over time with an average purchase price of USD $4.48.
Share price over the investment period. Source: S&P Capital IQ.
Why did we sell?
Acquisition by OpenText
In November 2021, OpenText Corporation (NASDAQ: OTEX) announced the acquisition of Zix Corporation for USD $8.50 per share in cash, representing a premium of ~26% over the closing price prior to the announcement.
Strategic premium realized: The offer crystallised the company’s strategic value, allowing shareholders to exit at a significant premium.
Diminished standalone upside: With valuation multiples re-rated and integration underway, future returns were likely to be more modest under OpenText’s ownership.
Capital reallocation: Proceeds from the sale were redeployed into higher-conviction opportunities in the small-cap tech space with greater upside potential.
Investment outcome
Began initially purchasing shares in April 2016 at USD $3.99 and continued to purchase over time with an average purchase price of USD $4.48.
Sold at an average sale price of USD $8.12 with the last sale in December 2021 at USD $8.50.
Gain of 81.2% on our investment over the period, equating to a money weighted IRR of approximately 18.3%.
*Past performance is not indicative of future performance. This is general information only and should not be construed or relied upon as legal, financial or professional advice. Accordingly, the recipient should seek independent professional advice as to the risk, financial, taxation and other implications of investing. Microequities Asset Management Pty Ltd is a Corporate Authorised Representative (CAR 462438) of AFSL 287526.